Table of Contents
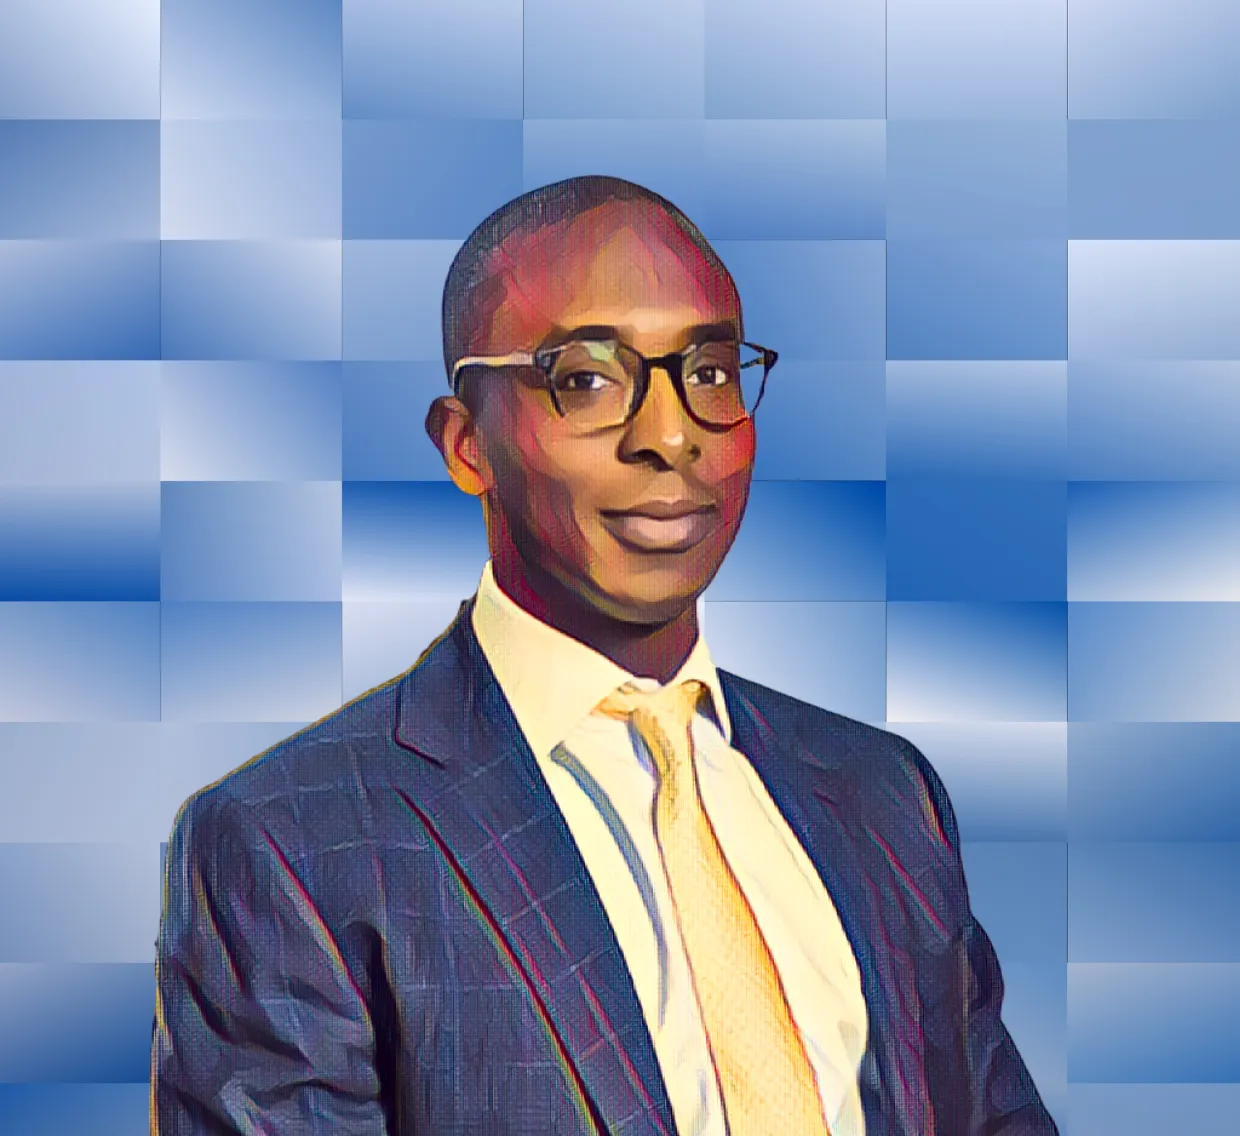
Fola Aiyesimoju, the former Kohlberg Kravis Roberts & Co. dealmaker who runs UAC of Nigeria Plc, owns a personal stake in the Lagos-listed company now worth about ₦14.8 billion ($10.8 million), after its shares almost doubled this year.
Aiyesimoju holds 86,014,099 UAC shares in his own name, or 2.94% of the company. UAC shares traded at ₦172 on Friday, giving the holding a value of about ₦14.79 billion. That makes him one of the largest individual shareholders in the 147-year-old conglomerate he has led as group managing director since 2019.
The stake is separate from the much larger block held by Themis Capital Management, the investment firm Aiyesimoju founded. Themis is UAC's biggest shareholder, with 586,289,403 shares, or about 20% of the company, worth about ₦100.8 billion ($73.9 million) at Friday's price. Its filings do not disclose who owns Themis or in what proportions, so that block is not counted toward Aiyesimoju's personal holding.
A strong run for the shares
UAC shares have risen about 89% this year. They closed at ₦181 on Oct. 30, up 98.9% for the year, before slipping in a broad sell-off on the Nigerian Exchange this week. At the start of January, Aiyesimoju's personal shares were worth about ₦7.8 billion, so their value has risen by roughly ₦7 billion ($5.1 million) since then.
The rally follows a 207% gain in 2025, when the stock rose from ₦32.95 at the start of the year. In May 2021, when Aiyesimoju bought 22.5 million UAC shares at ₦10.30 each for about ₦231.7 million, the stock traded at about ₦10. UAC now has a market value of about ₦503 billion ($369 million).
The surge has been driven by the biggest deal of Aiyesimoju's career: the purchase of CHI Ltd., the maker of Chivita juices and Hollandia dairy drinks, from The Coca-Cola Co.
From Lagos to KKR
Aiyesimoju studied estate management at the University of Lagos, where he received a certificate of excellence in real estate development and finance. He qualified as a CFA charterholder in 2006.
He began his career at ARM Investment Managers, a Lagos asset manager, and at Ocean and Oil Holdings Ltd., a Nigerian principal investment firm. He then joined Standard Bank Group, where he spent about eight years, five of them running its mergers and acquisitions advisory business in Nigeria, and also served as head of financial advisory at Stanbic Capital, the group's local investment banking arm. While there, he worked on the 2013 acquisition of Fan Milk, the West African frozen dairy maker, by Danone SA and Abraaj Group, a deal worth about €120 million ($134 million).
From Standard Bank he moved to Kohlberg Kravis Roberts, the U.S. private equity firm, where he worked on investments in Africa. He later left to set up Themis with Peter Mombaur, a former McKinsey & Co. engagement manager who had co-run Tana Africa Capital. The firm describes its approach as concentrating capital and talent on a small number of high-potential businesses in sub-Saharan Africa. Aiyesimoju also co-founded Foodpro Ltd., a Nigerian maker of nut-based snacks.
Taking over UAC
UAC traces its roots to 1879 and for decades was part of Unilever's United Africa Co. By the time Themis arrived, it was a sprawling group with interests in food, paint, animal feed, real estate and logistics.
Themis disclosed a significant stake in UAC in February 2018, alongside two other investors, and kept buying. Aiyesimoju was appointed group managing director in April 2019.
His strategy has been to cut UAC back to a smaller number of businesses. The group sold control of its real estate unit, UPDC Plc, to Custodian Investment in 2020, and it has since agreed to sell its 43% stake in DP World Logistics and its 73.29% holding in Livestock Feeds Plc, both subject to regulatory approval. It has kept its paint business, Chemical and Allied Products Plc, and its packaged food and drinks unit.
The CHI deal
The decisive move came in July 2025, when UAC agreed to buy CHI from Coca-Cola. The deal closed in October 2025. UAC paid for it with ₦30.8 billion from its own reserves and a ₦151.6 billion dollar-denominated bridge loan, and it has lined up a seven-year naira loan and a ₦150 billion bond programme to refinance the debt. Aiyesimoju has said the timing reflected market conditions, including lower valuations and less competition for assets. The shares nearly doubled in July 2025, when the agreement was announced.
The purchase has changed the scale of the company. In the nine months to September 2026, UAC's revenue more than tripled to ₦523 billion ($383 million). Pre-tax profit rose 262.5% to ₦37.69 billion ($27.6 million), and profit after tax increased 307.1% to ₦21.91 billion ($16.1 million). Packaged food and beverages now make up about 83% of sales.
The deal also loaded the group with debt, and net finance costs rose to ₦23.94 billion in the nine months from ₦5.74 billion a year earlier. UAC has been paying it down. Borrowings fell 23.8% to ₦262.63 billion by the end of September, and net debt fell to about 2.2 times earnings before interest, tax, depreciation and amortization, from 5.9 times.
Aiyesimoju sits on the boards of several UAC subsidiaries, including Chemical and Allied Products, Grand Cereals Ltd. and UAC Foods Ltd.
Figures were converted at ₦1,365 to the dollar and €1 to $1.12.
The intelligence satisfies curiosity. The paid briefings satisfy strategy.
Every Monday, Elite subscribers receive an Investor Memo breaking down the deal, the structure and the positioning behind the week's most consequential African wealth story — the kind of analysis that doesn't appear anywhere else.
Twice a month, a Wealth Intelligence brief profiles a single billionaire's holdings, cash flows and expansion pipeline in detail no public source matches.
→ Executive ($25/mo): Daily newsletter + Deep-Dive Reports
→ Elite ($75/mo): Everything above + Investor Memos + Wealth Intelligence + Quarterly Analyst Briefings
Subscribe now